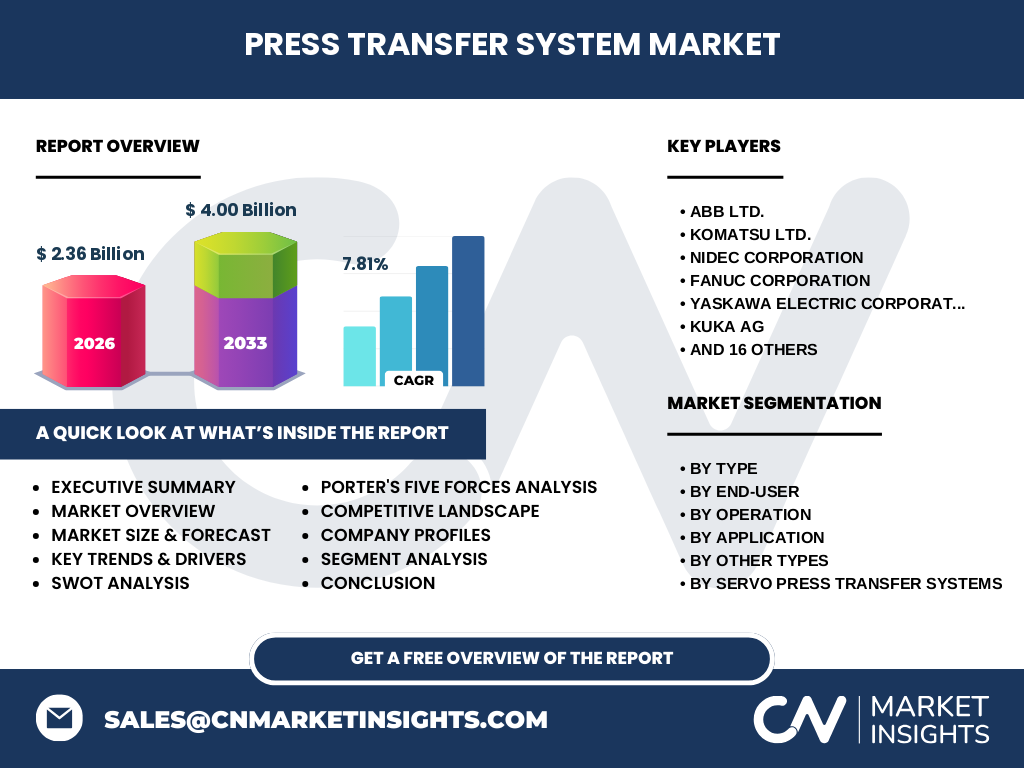
Market overview of the Press Transfer System Market
Our analysis indicates that the Press Transfer System Market achieves a valuation of 2.36 Billion in 2026, driven by high-speed automation demands. This ecosystem encompasses specialized material handling machinery designed to move stamped workpieces between press stations seamlessly. Crucial for heavy automotive stamping and white goods manufacturing, these systems utilize raw materials like specialized tool steel and aluminum alloys. Compliance with ISO 13849 safety standards governs the operational parameters across global manufacturing hubs.
Structural Growth Drivers and Restraints in the Press Transfer System Market
The market thrives on strict automotive lightweighting initiatives requiring complex multi-axis configurations. Key growth drivers include the transition to Electric Vehicle body structures, which necessitates high-precision part transfer. Conversely, primary market restraints involve prohibitive capital expenditure requirements for small-tier suppliers. Logistics hurdles regarding the transport of massive multi-ton press frames also restrict rapid deployment, heavily impacting supply chain velocity across North American and European industrial corridors.
Emerging Trends in the Press Transfer System Market
Industry trends highlight a definitive pivot toward servo-driven transfer integration over traditional mechanical linkages. Smart manufacturing paradigms now incorporate IoT-enabled vibration sensors and predictive maintenance algorithms within the Press Transfer System Market. These technological shifts favor agile automation providers capable of delivering custom-tailored software interfaces that synchronize seamlessly with existing plant floor programmable logic controllers, minimizing costly line changeover downtime.
COVID-19 Impact Analysis on the Press Transfer System Market
The pandemic severely disrupted global supply chains, halting factory acceptance tests and delaying large-scale automotive retooling projects worldwide. Pandemic-induced supply shocks forced OEMs to reassess localized sourcing strategies for critical pneumatic components and hydraulic actuators. However, the subsequent recovery trajectory has accelerated digital commissioning tools, allowing engineering teams from Schuler AG and ABB Ltd. to perform virtual buy-offs and remote troubleshooting, safeguarding project timelines.
Competitive Benchmarking in the Press Transfer System Market
The competitive landscape exhibits a high degree of consolidation among tier-one automation conglomerates and specialized press builders. Strategic positioning relies heavily on proprietary control software and multi-axis synchronization capabilities. Industry giants like Komatsu Ltd., Nidec Corporation, and Fanuc Corporation dominate through extensive global service networks. Smaller regional players carve out niches by offering highly customizable hydraulic and mechanical transfer solutions tailored to localized Tier-1 automotive suppliers.
Executive Summary of the Press Transfer System Market
Our comprehensive research demonstrates that the Press Transfer System Market is poised for exceptional expansion, scaling from 2.36 Billion in 2026 to an impressive 4.00 Billion by 2033. Propelled by a robust CAGR of 7.81%, the sector reflects surging global demand for intelligent automation. Key findings emphasize that early adoption of servo and robotic transfer technologies remains the primary differentiator for market leaders navigating tight labor markets.
Long-Term Market Forecast for the Press Transfer System Market
Projected growth from 2027 to 2033 highlights a sustained upward trajectory, culminating in a market valuation of 4.00 Billion by the end of the forecast period. This steady expansion, maintaining a 7.81% CAGR, is underwritten by continuous EV platform revamps and smart factory investments. Equipment manufacturers focusing on energy-efficient direct-drive servo systems will capture disproportionate revenue shares as sustainability mandates tighten globally.
Segmentation Analysis of the Press Transfer System Market
Market segmentation details reveal distinct operational preferences across various industrial verticals.
- By Type: Mechanical, Hydraulic, Servo, Pneumatic, and Other Systems.
- By End-User: Original Equipment Manufacturers and Aftermarket sectors.
- By Operation: Manual, Semi-Automatic, and Automatic configurations.
- By Application: Automotive, Aerospace, Electronics, and Consumer Goods.
- Specialized Sub-segments: Magnetic, Robotic, Hybrid, and Custom transfer technologies, alongside advanced servo and hydraulic variants.
Geographic Distribution and Regional Performance
Geographic performance in the Press Transfer System Market reflects heavy concentration in regions with dense automotive and electronics manufacturing bases. Asia-Pacific leads consumption due to aggressive industrial automation drives in China, Japan, and South Korea, involving key regional players like Yaskawa Electric Corporation and JIER Machine Tool Group. Meanwhile, North America and Europe focus heavily on high-precision retrofit projects managed by established enterprises such as AP&T Group and Fagor Arrasate.
In-Depth Regional Review
Asia-Pacific commands the lion's share of market demand, anchored by robust automotive production clusters in Shenzhen, Nagoya, and Ulsan. Regulatory frameworks such as China's National Safety Standards heavily influence machine safeguarding protocols. Conversely, European markets prioritize energy efficiency and ergonomic modularity, with German and Spanish engineering firms pioneering closed-loop energy recovery systems within their high-speed mechanical and servo press transfer lines.
Strategic Positioning of Leading Companies
Market leaders employ distinct strategies to maintain dominance within the Press Transfer System Market. ABB Ltd. and Kuka AG leverage advanced robotic integration expertise, whereas Schuler AG and Komatsu Ltd. combine press design mastery with proprietary transfer mechanics. Specialized innovators like Gudel Group AG and Macrodyne Technologies Inc. focus on heavy-payload custom gantries and robust hydraulic systems, capturing specialized industrial niches.
Porter's Five Forces Analysis of the Sector
Industry dynamics evaluated through Porter's framework indicate moderate-to-high competitive rivalry among established multinational press automation providers. Threat of new entrants remains low due to significant intellectual property barriers, massive tooling capital requirements, and stringent safety certifications. Bargaining power of buyers is substantial among major automotive OEMs who demand customized engineering, while supplier power over specialized servo motors and high-grade steel remains balanced.
SWOT Analysis of the Press Transfer System Market
Strengths include unmatched production throughput and high repeatability in mass-manufacturing environments. Weaknesses stem from high initial capital outlays and complex maintenance requirements. Opportunities abound in emerging electronics manufacturing hubs across Southeast Asia. Threats involve raw material price volatility for structural steel and unpredictable geopolitical trade tariffs impacting global supply chains for automation hardware.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material providers supplying high-grade alloy steels, aluminum, and rare-earth magnets for servo drives. Component manufacturers then fabricate specialized gearboxes, pneumatic cylinders, and CNC controllers. System integrators assemble these elements into cohesive transfer lines, which are subsequently commissioned by Tier-1 automotive and aerospace Original Equipment Manufacturers to optimize their high-speed stamping operations.
Investment Insights and Strategic Recommendations
Our analysis indicates that high-potential investment areas center around retrofit solutions that upgrade legacy mechanical presses with energy-efficient servo transfer systems. Venture capital and private equity should target agile technology innovators developing plug-and-play magnetic and hybrid transfer systems. Stakeholders must prioritize software integration capabilities to capitalize on the booming demand for smart, data-driven factory floors.
Conclusion and Key Takeaways
The Press Transfer System Market demonstrates exceptional resilience and growth, expanding from 2.36 Billion in 2026 to 4.00 Billion by 2033 at a 7.81% CAGR. Success in this evolving landscape demands continuous technological innovation, particularly in multi-axis servo synchronization and IoT-based predictive maintenance. Manufacturers embracing these advanced capabilities will capture long-term competitive advantages.
Research Methodology
Baseline estimates are triangulated using a rigorous multi-tier research methodology. This approach combines customs trade registry data, primary stakeholder interviews with chief engineering officers at firms like ISGEC Heavy Engineering and Simpac Inc., and secondary macroeconomic indicators. Proprietary econometric modeling validates market sizing projections against historic automotive production indices and industrial capital expenditure reports.
Scope of the Report and Coverage Parameters
This report encompasses a global evaluation of the Press Transfer System Market, analyzing historical data from 2022 alongside forecasts spanning 2027 to 2033. Coverage parameters evaluate mechanical, hydraulic, servo, and pneumatic systems across five major geographic regions. Limitations include unforeseen macroeconomic shifts, regulatory policy overhauls in localized manufacturing jurisdictions, and sudden supply chain disruptions impacting specialized electronic component procurement.
Recent Industry Developments and Strategic Moves
Recent market activities feature aggressive joint ventures and strategic product launches aimed at enhancing automation flexibility. Companies like SEYI Machinery Industry and Chin Fong Machine Industrial have unveiled modular, high-speed multi-axis servo transfer lines designed to cut die-changeover times by half. Meanwhile, strategic acquisitions among European engineering firms underscore a consolidated push toward fully integrated, cloud-managed smart stamping ecosystems.